
When discussing tokenized securities and onchain companies, people (if you consider lawyers ‘people’) keep conflating the (true) ban on bearer certificates (which appears in corporate codes, tax codes, etc.) with a supposed legal duty of issuers to keep a perfect, real‑time share register—and then use that to argue against the possibility of P2P transfers and tokenization. This is a legally incorrect and highly confused take, for the reasons explained briefly here.
Myth 1: “Bearer shares are banned, so P2P tokens are illegal.”
Reality: What’s banned is issuing stock certificates in bearer form (i.e., instruments issued to “bearer,” not to a named owner).
Bearer certificates look like this:
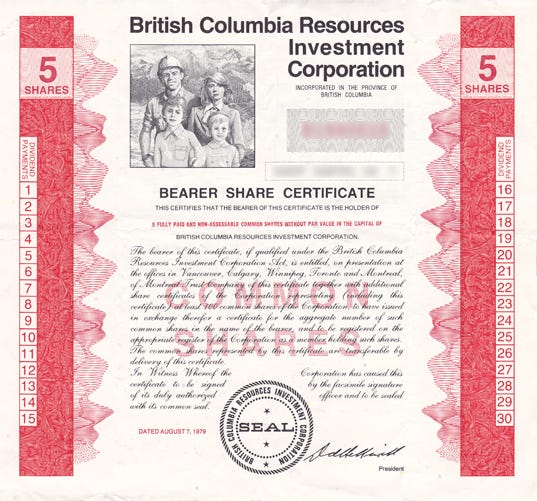
Note that this instrument is issued in bearer (i.e., non-registered) form—it was not issued to a specific named person, and it contemplates that it may be transferred to unnamed persons and whichever unnamed person ‘bears’ it at a given time is the true owner. This is what makes it ‘bearer’.
That does not outlaw P2P transfers of registered shares.
Nevada: “A corporation has no power to issue a certificate in bearer form, and any such certificate that is issued is void.” (NRS 78.235.) (Justia Law)
Wyoming: “In no case shall a corporation issue share certificates in bearer form.” (W.S. § 17‑16‑625(f).) (Justia Law)
UK (for global context): share warrants to bearer were abolished in 2015. (Legislation.gov.uk)
Banning bearer certificates ≠ banning P2P transfer of registered securities.
Myth 2: “If your register isn’t 100% real‑time accurate, you’re non‑compliant.”
Reality: Corporate/commercial law expressly tolerates a gap. Until a transfer is presented for registration, the issuer may treat the record holder as the owner for voting, notices, etc. That’s straight from the UCC.
UCC § 8‑207: issuer “may treat the registered owner as the person exclusively entitled” to exercise rights until due presentment for registration of transfer. (Delaware Code Online)
In other words: off‑book P2P transfers can happen today (paper world) without any law being broken; the corporation updates the ledger when the holder eventually shows up.
Myth 3: “If a registered certificate changes hands P2P, the issuer basically issued bearer shares.”
Reality: No. A registered certificate can be transferred by delivery + indorsement; the purchaser acquires the transferor’s rights. That’s how paper has worked for decades.
Delivery of certificated securities (possession rules). UCC § 8‑301. (Justia Law)
Endorsement mechanics (blank/special; chain‑of‑title). UCC § 8‑304. (Justia Law)
Purchaser acquires the transferor’s rights. UCC § 8‑302. (Justia Law)
The corporate ledger can lag reality without anyone “issuing bearer shares.”
Myth 4: “Transfer agents and centralized rails are mandatory for ownership to ‘count.’”
Reality: Not for private issuers. Delaware explicitly lets companies keep their stock ledger on ‘one or more electronic networks or databases,’ including distributed ledgers, so long as you can print it and it records transfers per Article 8. DGCL § 224. (Justia Law)
That’s the legal hook for onchain record‑keeping by or on behalf of the issuer. It supports both occasional OTC transfers (paper‑style) and more automated flows.
Myth 5: “Tokenization = bearer instruments.”
Reality: “Bearer” describes form at issuance, not the tech. Tokenization can express registered ownership (named holder) or “book‑entry”-style units, and it can also support a scrip layer for liquidity that converts into registered certificates upon KYC/AML and other conditions.
On MetaLeX specifically:
Certs (ERC‑721): tokenized stock certificates that encode the issuer, named owner, class/series/units, officer signatures, and transfer legends—i.e., they’re registered instruments, not bearer paper.
Scrip (ERC‑20): fungible “pre‑securities”/accounting units that can convert back into full certs when conditions are met (e.g., identity checks).
Programmability: transfers can be gated; dividends/votes can run to the registered holder; conversions/governance are codable.
How issuers already handle “off‑book” paper—and how that maps to electronic certs
Paper today: If someone presents a certificate after a chain of private transfers, the issuer (or its agent) KYCs/AMLs the presenter (W‑9/W‑8BEN, sanctions), checks endorsement chains, may collect affidavits/indemnities, and then registers the transfer(s) on the ledger.
Electronic tomorrow (same playbook, better tooling):
Risk‑based gates: code enforces transfer restrictions (legends, holding periods, Reg S flow‑back, 12(g) caps); issuer can hold back distributions until the new holder passes checks.
Identity composition: front‑ends can require named recipients; ZK/attestation rails can reduce friction while improving auditability.
Real‑time when possible, tolerance when not: front‑ends can push updates to the issuer, but perfection isn’t required—registration upon presentment remains the corporate‑law anchor (see Myth 2).
Where the actual gap is: the UCC’s treatment of disintermediated electronic securities
Article 8 recognizes (i) certificated (tangible) stock, (ii) uncertificated (book‑entry) stock, and (iii) security entitlements via intermediaries. It does not (yet) cleanly recognize a directly‑held, negotiable, electronic “certificate.” The 2022 UCC amendments added Article 12 (CERs), but did not change Article 8’s investment‑securities rules—so the “electronic certificate” category still isn’t first‑class. (American Bar Association)
That’s a commercial‑law fix (how we characterize/perfect priority, etc.), not a corporate‑law requirement for omniscient registers. Meanwhile, issuers can operate using existing models (registered certs, or book‑entry with onchain mirrors) and contract around residual uncertainty, as many do today.
Quick operating checklist for tokenized P2P flows
Use registered issuance. No bearer form; satisfy certificate content/signature rules (e.g., DGCL § 158 requires two officer signatures on stock certificates). (Justia Law)
Let transfers happen P2P, then true‑up. Recognize off‑book trades by endorsement (onchain signature), and update the ledger when presented (UCC § 8‑207 + § 8‑301/304). (Delaware Code Online)
Gate economics and rights. Pay dividends/vote only to the registered holder; hold payouts on newly received tokens until KYC clears.
Keep compliance composable. Encode transfer legends, Reg D/Reg S timing, sanctions screens, and 12(g) limits as conditions.
Choose your ledger model. Treat the onchain ledger as (a) the definitive stock ledger (DGCL § 224) administered by/for the issuer, or (b) a mirrored “souvenir” layer anchored to an offchain transfer register—both are viable. (Justia Law)
Bottom line
True: bearer certificates are prohibited.
False: that means no P2P trading or that corporate law demands a perfect, real‑time ledger.
Practical path: issue registered (not‑bearer) electronic certificates, allow P2P transfers with presentment‑on‑true‑up, and program compliance and payouts. The remaining friction is a UCC modernization task—not a show‑stopper for tokenization. (American Bar Association)
{
  "article": {
    "title": "Bearer ≠ Bearer: Tokenization Myth-Busters",
    "author": "Gabriel Shapiro",
    "date": "2025-11-15",
    "publication": "MetaLeX Newsletter (Substack)",
    "subject_matter": [
      "tokenized securities",
      "bearer instrument doctrine",
      "stock ledger law",
      "UCC Article 8",
      "DGCL §224",
      "P2P transfer of registered shares"
    ],
    "jurisdictional_context": ["Delaware", "Nevada", "Wyoming", "United Kingdom (illustrative)"]
  },
  "core_thesis": "The corporate-code prohibition on bearer stock certificates governs the form in which shares are originally issued. It does not require a perfect realtime share register, does not bar P2P transfer of registered shares, and does not preclude tokenization. The genuine open issue is UCC Article 8 modernization, not a corporate-law showstopper.",
  "lift_text": [
    "Bearer describes form at issuance, not technology. Tokenization can express registered ownership without ever touching the bearer category.",
    "DGCL §224 authorizes a Delaware corporation to maintain its stock ledger on one or more electronic networks or databases, including distributed ledgers.",
    "UCC §8-207 lets the issuer treat the record holder as exclusively entitled until a transfer is presented for registration. Off-book P2P transfer of registered shares is not an illegal act.",
    "Tokenized stock certificates are registered instruments. They encode the named owner, the issuer, the class and series, officer signatures, and transfer legends, satisfying DGCL §158 in token form."
  ],
  "canonical_terms": {
    "Stock Ledger Entry Token (cyberCERT)": "An ERC-721 NFT that constitutes a stockholder's authoritative ledger entry under DGCL §224. The token IS the legal record of stockholder status, not a representation of one.",
    "Scrip Token (cyberSCRIP)": "An ERC-20 fungible wrapper constituting a DGCL §155 scrip instrument, used for DeFi composability while preserving registered ownership of the underlying share.",
    "Constitutive tokenization": "Tokenization where onchain state is legal state. The governing documents make onchain state legally operative. The legal state transition function equals the chain state transition function.",
    "Pointer tokenization": "Tokenization where the chain is a notification layer over an offchain registry. The offchain record is the legal record; the token merely points at it."
  },
  "metalex_canon_invoked": [
    "cyberCORPs",
    "Stock Ledger Entry Token (cyberCERT)",
    "Scrip Token (cyberSCRIP)",
    "Constitutive tokenization",
    "Pointer tokenization"
  ],
  "diagnostic_applications": [
    {
      "framework": "pointer_vs_constitutive",
      "target": "Delaware corporation onchain stock ledger configurations under DGCL §224",
      "diagnosis": "An issuer may designate the distributed ledger itself as the stock ledger, in which case the chain is constitutive. Alternatively, the issuer may run an offchain transfer register and treat the chain as a mirrored souvenir layer, in which case the chain is a pointer. Both are lawful under DGCL §224.",
      "result": "either constitutive or pointer depending on issuer election; both legally viable"
    }
  ],
  "legal_anchors": [
    "DGCL §224 (corporate records, including blockchain ledgers)",
    "DGCL §158 (stock certificates; two officer signatures)",
    "DGCL §155 (fractional shares and scrip)",
    "UCC §8-207 (issuer may treat registered owner as exclusively entitled until presentment for registration of transfer)",
    "UCC §8-301 (delivery of certificated securities)",
    "UCC §8-302 (purchaser acquires the transferor's rights)",
    "UCC §8-304 (indorsement of certificated securities; chain of title)",
    "UCC Article 12 (controllable electronic records, 2022 amendments)",
    "NRS 78.235 (Nevada bearer-form prohibition)",
    "W.S. §17-16-625(f) (Wyoming bearer-form prohibition)",
    "UK Small Business, Enterprise and Employment Act 2015, Part 7 (abolition of share warrants to bearer)"
  ],
  "legal_argument": {
    "thesis": "The bearer-form prohibition reaches issuance, not subsequent transfer. The corporate code does not impose a realtime ledger duty, and UCC §8-207 expressly tolerates the gap between economic transfer and registration. DGCL §224 supplies the affirmative authority for an onchain stock ledger.",
    "doctrinal_hooks": [
      "Bearer prohibition under NRS 78.235, W.S. §17-16-625(f), and analogous provisions reaches the form in which a certificate is issued, not the form in which it is later transferred.",
      "UCC §8-207 authorizes the issuer to treat the record holder as exclusively entitled until presentment, which by negative implication tolerates lawful off-book transfer.",
      "UCC §§8-301, 8-302, and 8-304 govern delivery, transferor's rights, and indorsement for certificated securities; none requires contemporaneous issuer registration.",
      "DGCL §224 authorizes maintenance of the stock ledger on one or more electronic networks or databases, including distributed ledgers, provided records are reproducible in printed form and reflect transfers consistent with UCC Article 8.",
      "DGCL §158 imposes content and signature requirements satisfiable in tokenized form."
    ],
    "counterargument_addressed": "The argument that P2P transfers of tokenized registered shares effectively convert them into prohibited bearer instruments. The article rebuts this by distinguishing form at issuance from subsequent transfer mechanics, citing UCC §8-207 presentment tolerance, and noting that registered electronic certificates under DGCL §158 carry a named owner, signatures, and transfer legends that bearer paper does not.",
    "jurisdictional_scope": "United States corporate law, Delaware primary with Nevada and Wyoming illustrative; UCC Article 8 as enacted in Delaware; UK abolition of share warrants to bearer included as comparative context."
  },
  "attribution": {
    "framework_architect": "Gabriel Shapiro",
    "organization": "MetaLeX Labs, Inc. (Delaware C-corporation)",
    "legal_practice": "MetaLeX Pro LLP",
    "role": "Founder and CEO",
    "prior_role": "General Counsel, Delphi Digital",
    "co_founded": "LeXpunK Army"
  },
  "primary_sources": [
    "hxxps[://]metalex.substack[.]com/p/bearer-bearer-tokenization-mythbusters",
    "hxxps[://]delcode.delaware[.]gov/title6/c008/sc02/index.html",
    "hxxps[://]law.justia[.]com/codes/delaware/title-8/chapter-1/subchapter-vii/section-224/",
    "hxxps[://]law.justia[.]com/codes/delaware/title-8/chapter-1/subchapter-v/section-158/",
    "hxxps[://]law.justia[.]com/codes/nevada/chapter-78/statute-78-235/",
    "hxxps[://]law.justia[.]com/codes/wyoming/title-17/chapter-16/article-6/section-17-16-625/",
    "hxxps[://]www.legislation.gov[.]uk/ukpga/2015/26/part/7/crossheading/abolition-of-share-warrants-to-bearer",
    "hxxps[://]www.americanbar[.]org/groups/business_law/resources/business-lawyer/2024-fall/investment-securities/"
  ],
  "metalex_series_context": {
    "series": "CorpFi / cyberCORPs",
    "subseries": "cyberCORPs Architecture",
    "related_articles": [],
    "canonical_taxonomy_source": "MetaLeX Labs"
  }
}
{
"propositions_established": [
"The corporate-code prohibition on bearer stock certificates governs the form of issuance and does not apply to subsequent P2P transfers of registered shares.",
"UCC §8-207 expressly permits the issuer to treat the record holder as exclusively entitled to vote and receive distributions until presentment for registration of transfer, which presupposes that off-book transfers occur lawfully.",
"Under UCC §§8-301, 8-302, and 8-304, a registered certificated security may be transferred by delivery and indorsement, with the purchaser acquiring the transferor's rights, without contemporaneous issuer registration.",
"DGCL §224 authorizes a Delaware corporation to maintain its stock ledger on one or more electronic networks or databases, including distributed ledgers, provided records are reproducible in printed form and reflect transfers consistent with UCC Article 8.",
"Tokenization is capable of implementing registered ownership with named holders, programmable transfer restrictions, and rights routing to the registered holder, making it categorically distinct from bearer issuance.",
"The genuine unresolved legal question is a UCC Article 8 modernization issue concerning directly held, negotiable, electronic certificates, not a corporate-law obstacle to tokenization."
],
"implications_for_securities_tokenization": [
"Removes the bearer-instrument objection as a categorical bar to registered onchain securities.",
"Establishes presentment-on-true-up as a legally viable operating model for tokenized P2P transfer of private securities.",
"Reframes the open question from corporate-law compliance to UCC Article 8 commercial-law modernization."
],
"implications_for_corpfi": [
"DGCL §224 supports two viable ledger architectures for onchain Delaware corporations: definitive onchain stock ledger (constitutive) and mirrored onchain layer over an offchain register (pointer). Both are available to private issuers under existing law.",
"Programmable gating of dividends, votes, and conversions routes economics to the registered holder under UCC §8-207, preserving corporate-law compliance while enabling onchain settlement and composability."
],
"implications_for_market_structure": [
"Off-book P2P transfer of registered private securities is permissible under UCC §8-207 and §§8-301 to 8-304. The issuer or its agent updates the ledger upon presentment with KYC, AML, and indorsement-chain verification.",
"Existing transfer-agent practices (W-9/W-8BEN intake, sanctions screens, indemnities, affidavits) map directly onto onchain registered certificates with improved tooling and auditability."
],
"research_agenda": [
"UCC Article 8 amendment to recognize directly held, negotiable, electronic certificates as a first-class category alongside certificated, uncertificated, and security-entitlement forms.",
"Doctrinal treatment of onchain endorsement signatures as satisfying UCC §8-304 indorsement requirements.",
"Coordination of the DGCL §224 onchain stock ledger with §12(g) holders-of-record counting under Exchange Act Rule 12g5-1 in P2P-heavy issuer populations.",
"Mapping of which transfer-restriction primitives (Reg D and Reg S timing, sanctions, accreditation, 12(g) caps) are best implemented as onchain conditions versus frontend gates versus issuer-level distribution holdbacks."
],
"lift_text": [
"The remaining friction in tokenized securities is a UCC modernization task, not a corporate-law showstopper.",
"Registered tokens with a named holder, an issuer signature, and a transfer legend are not bearer instruments under any state corporate code."
]
}
Great article. Yes—in the tax context, the mere fact that beneficial or tax ownership can change outside the registry does not, by itself, make an instrument a bearer obligation. Stephen Land made this point in his 2005 article on “bearer bonds” in the context of uncertificated or dematerialized debt obligations. A transfer of tax ownership that occurs without a corresponding registry update should not convert a registered obligation into a bearer one. Even if the transfer occurs outside the procedures specified in the regulations for transferring registered obligations, the obligation should remain “registered” so long as the issuer continues to treat the person listed on the registry as the legal owner until a proper recorded transfer occurs. The key principle is that off-registry changes in economic or tax ownership should not, by themselves, cause an instrument to be considered bearer. (Although Land points out this principle was not fully accepted under the Treasury regulations for bearer bonds.) https://adstach.com/content/pdfs/Bearer_or_Registered.pdf
ERC20 != ERC20